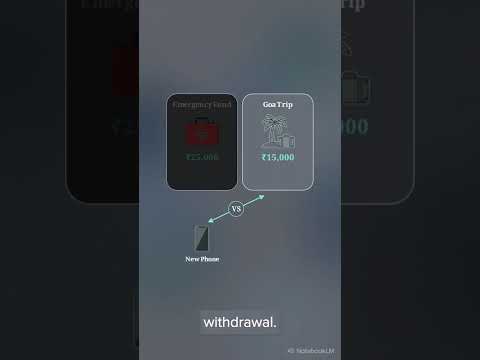
A small psychological trick makes saving noticeably easier: give your money a name. A pot labelled "savings" is easy to raid for any passing want. A pot labelled "Goa trip" or "monsoon buffer" feels like it already belongs to something — and dipping into it feels like stealing from a plan you care about. The label does quiet work your willpower otherwise has to.
Here's how to use it. Instead of one undifferentiated savings balance, split your saving into named goals: "emergency fund," "Diwali," "new laptop," "daughter's school fees." Each gets its own target and its own progress. Now when you're tempted to spend, you're not weighing it against a vague pile of money — you're weighing it against a specific thing you've decided you want more.
Why this works comes down to how we treat money mentally. We're far more protective of funds that have a purpose than funds that don't. A ₹40,000 "general savings" balance feels spendable; ₹40,000 split as "₹25,000 emergency + ₹15,000 trip" feels spoken-for. Same money, very different temptation.
Practically, you can do this with separate goals or simply by tracking named targets against your savings. Watching a named goal fill up is also genuinely motivating — progress toward "trip: 70% there" pulls you forward in a way a flat balance never does. Give every chunk of saving a job and a name. It turns abstract discipline into something concrete and personal, and makes the money far stickier when temptation comes calling.