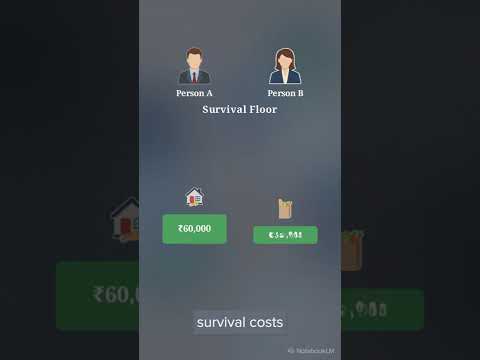
"How big should my emergency fund be?" has a simple answer that trips people up anyway: size it on expenses, not income. If you earn ₹80,000 but only spend ₹40,000 a month on genuine essentials, your fund target is based on that ₹40,000 — not the bigger number sitting on your payslip.
Here's the math. Three months of essentials at ₹40,000 is ₹1.2 lakh. Six months is ₹2.4 lakh. Notice that lifestyle spending — dining out, subscriptions, shopping — doesn't belong in this calculation at all. In a genuine emergency, those are the first things you'd cut anyway, so there's no need to fund them with emergency reserves.
Why income is the wrong yardstick: two people earning the same ₹80,000 can have very different emergency needs if one spends ₹60,000 on essentials and the other spends ₹35,000. The fund exists to cover survival spending during a shock, and survival spending is what actually varies between households — not take-home pay.
To find your real number, list only the unavoidable monthly costs: rent or EMI, groceries, utilities, basic transport, insurance premiums, minimum debt payments. Multiply that by three for a starting target, six if your income is irregular. This number is also useful beyond emergencies — it's the true floor of what your life costs, which is worth knowing regardless of how big your fund eventually gets.